Cheapest Car to Insure New Driver Uk
 著者: 吉田 誠
Now, before you buy, remember: the car is only half the battle. You can halve your premium again with a few smart moves. First, add an older, experienced driver as a named secondary driver on your policy. This is not fraud—it’s called “fronting” only if they’re the main driver. So don’t lie. But if your mum or dad adds their clean record to the mix, insurers often lower the risk score. It’s like having a DJ Khaled feature on your song: suddenly the track sounds safer.
Second, always compare quotes using a price comparison site. But don’t just pick the cheapest. Check the excess—if it’s £1,500, you might as well be uninsured. Look for policies with a low voluntary excess (aim for £250 or less). Oh, and never auto-renew. Loyalty is for dogs and marriages, not car insurance. Shopping around can save you up to £400.
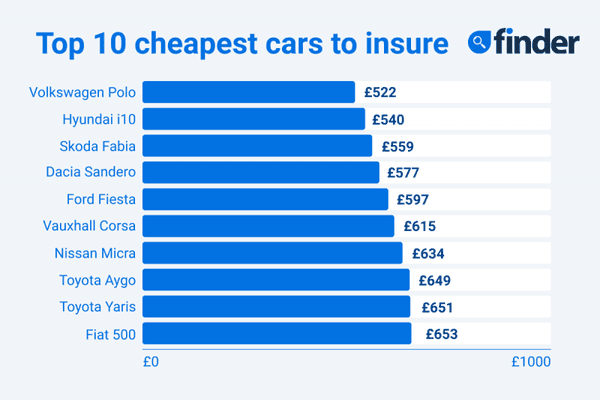 Cheapest cars to insure UK | See our top 10 | Finder UK
Third, consider a black box telematics policy. Yes, it feels like having your nan in the passenger seat judging your Revs-per-minute. But for new drivers, it can slash premiums by up to 40%. Drive smoothly, avoid 3am trips, and you’ll earn a discount. Plus, it’s a great excuse to tell your mates you can’t drive them to Tesco at 2am: “Sorry, the black box will grass on me.”
A Cultural Note
Remember that classic Top Gear episode where Hammond bought a cheap hatchback? That’s the energy you need. You’re not buying a status symbol; you’re buying mobility. In the UK, a first car is a rite of passage—like making beans on toast for the first time or surviving a Wetherspoons’ floor at closing time. It’s not glamorous, but it’s yours.
Insider tip: check Facebook Marketplace for city cars with a full service history. A 2012 Fiat Panda with 60k miles and a dusty owner’s manual might be your golden ticket. Just avoid anything modified with a “sports” exhaust or tinted windows—that screams “I’m a risk” to insurers.
最新のテクノロジーと生活デザインの融合をテーマに、国内外の最新トピックを発信しています。
