Va Investment Property Loan
 著者: 斉藤 蓮
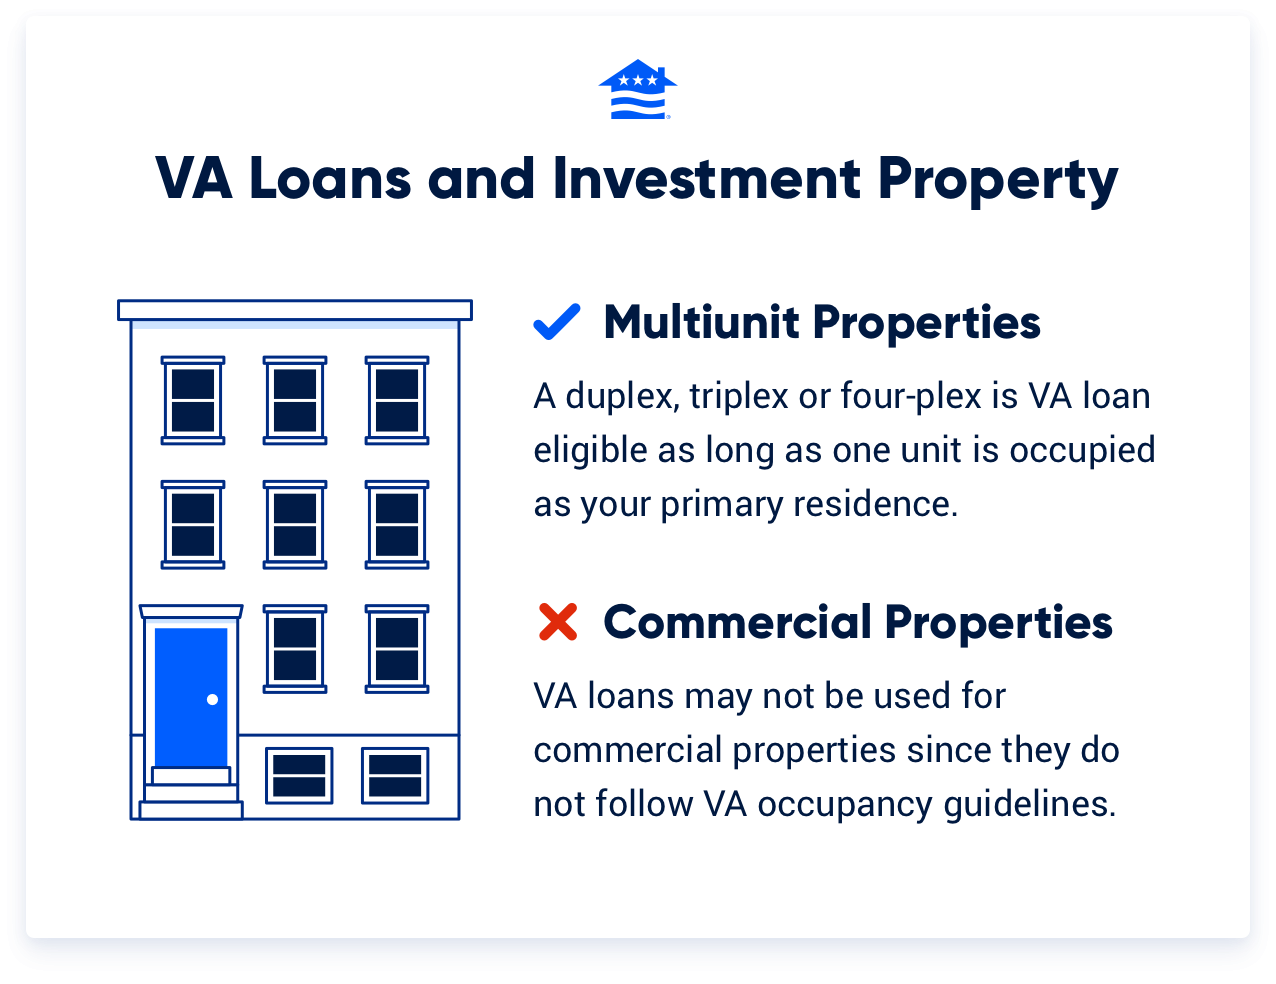
Here’s where the smooth jazz stops for a second. The VA requires a funding fee (2.15% for subsequent use), unless you have a service-connected disability. That fee can be rolled into the loan, but it adds to your monthly payment. Also, the property must meet Minimum Property Requirements, or MPRs—no crumbling roofs or leaky pipes. Think of it as a landlord exam: the VA wants proof the unit is safe for you to live in.
Practical tip: Use a lender who specializes in VA loans for investment properties. Not all loan officers know the nuance of renting out extra units while you live in one. Ask them, “Have you closed a VA house hack in the last six months?” If they hesitate, run. You want someone who treats the VA like a scalpel, not a hammer.
Another fun fact: The VA doesn’t limit how many units you can own, just how many you can use this benefit for simultaneously. You can have multiple VA loans for investment properties, as long as you’ve restored your entitlement (usually by selling the first property or paying off the loan). It’s like a loyalty card for veterans—except instead of getting a free coffee, you get a passive income stream.
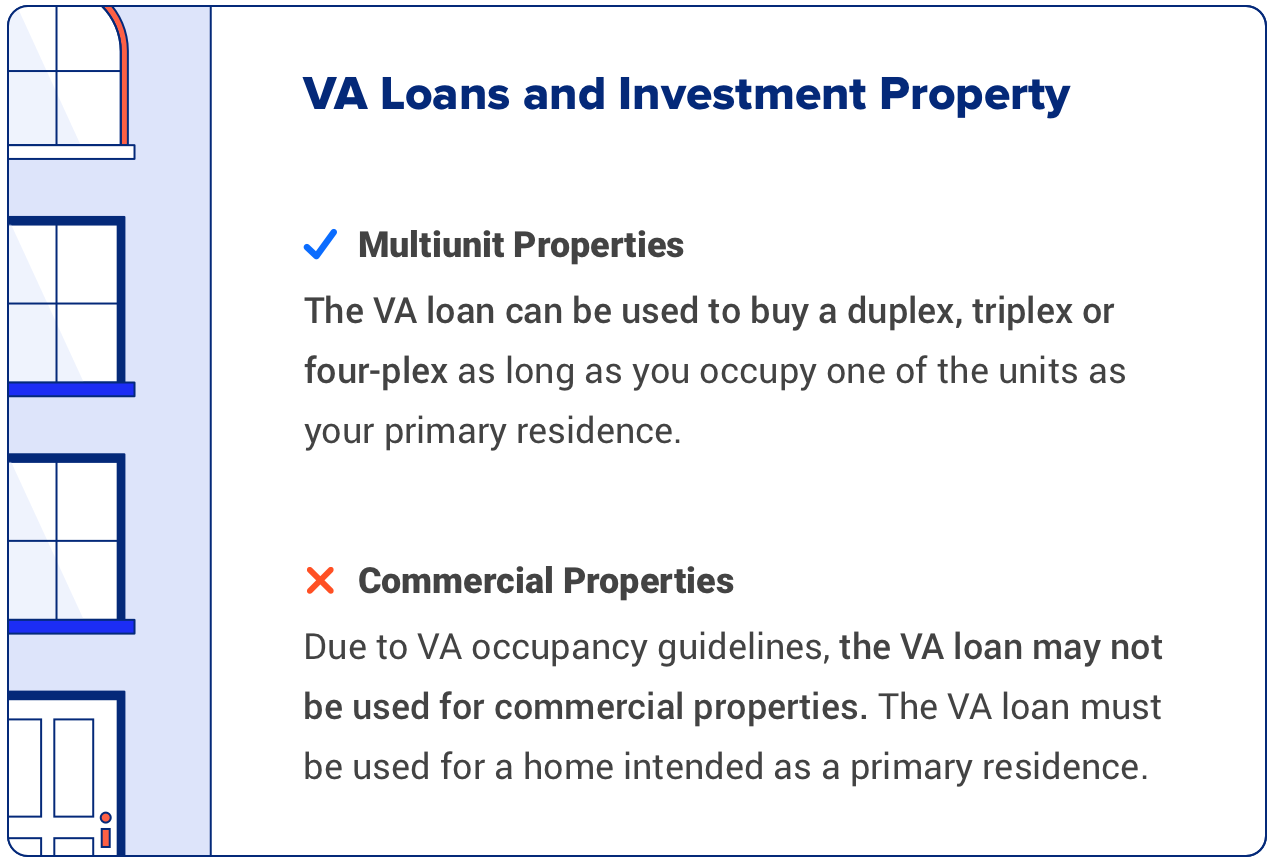 Can You Use Va Loan For Investment Property? - Get Money Saving
Making It Work in the Real World
Let’s talk numbers. In 2026, the average rental income for a two-bedroom unit in a duplex in a mid-tier city like Richmond, VA, is about $1,500 per month. If your mortgage (with zero down, at 6.5% interest) is $2,800 for the whole building, and you live in one unit, the other two units could cover $3,000. That’s negative rent for you—you’re living for free while building equity. It’s the financial equivalent of ordering a pizza and getting a free dessert because the app glitched.
Cultural reference time: Remember the scene in The Social Network where Mark Zuckerberg says, “A million dollars isn’t cool. You know what’s cool? A billion dollars.” You don’t need a billion. You just need one tenant who pays on time. Consistency beats big swings in real estate.
Biggest caution: Don’t overleverage yourself. The VA loan’s zero-down feature is seductive, but your debt-to-income ratio still matters. Lenders usually cap it at 41% for VA loans. That means your new mortgage plus existing debts (car, student loans, credit cards) can’t exceed 41% of your gross income. Punch those numbers on a napkin before you get starry-eyed.
シンプルで洗練された住まいづくりとインテリアコーディネートのアイデアを提案しています。
